Read what was denied, and why
Identify whether the letter denies the entire claim, a particular area or a particular type of expense. Note the stated cause and any policy provision, condition or exclusion cited. Keep the estimate and decision together; they answer different questions.
Arkansas § 15-107(b)(1) requires a written denial and reference to the policy wording when a denial is grounded in a provision, condition or exclusion. If the explanation is unclear, ask the insurer for the applicable wording and the facts used in its evaluation.
Compare the decision with the property record
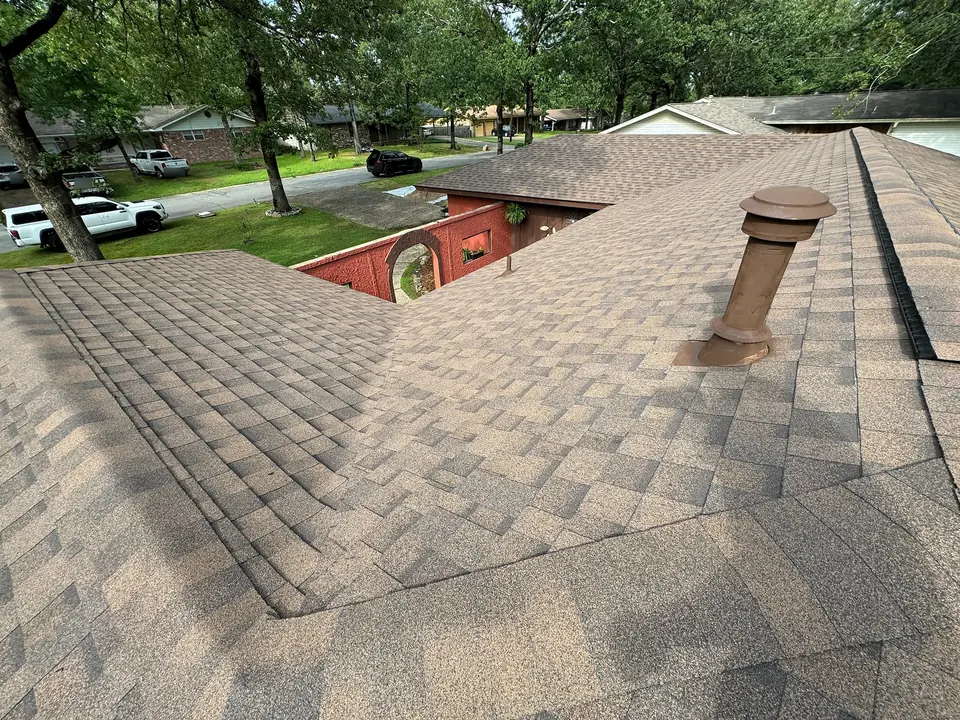
Organize dated photographs, inspection notes and any earlier roof records. Separate what was observed from assumptions about cause. If a photograph shows a different location than the disputed estimate item, identify the location clearly rather than submit a large unsorted image folder.
Do not change dates, exaggerate damage or describe pre-existing conditions as new damage. If a condition was concealed or inaccessible, say so. Honest records help the insurer evaluate relevant information and help a contractor understand what needs investigation.
Ask a specific written question
A useful question identifies the item, the explanation you received and the information you want clarified. For example: “Which inspection observation supports the conclusion about this roof area?” or “Which endorsement applies to this item?” Attach the relevant record, not unrelated documents.
Ask whether the insurer has a reconsideration or review process and what information it requires. Do not assume a health-insurance external-review procedure applies to a property claim. Keep copies of what you sent and any response.
Obtain construction documentation where useful
A contractor can describe visible roof conditions, measurements and repair considerations. A report may explain where damage appears, what remains uncertain and which construction operation is proposed. It should not claim that the insurer is legally required to pay the estimate.
Alden Stone may inspect, prepare construction records and explain scope questions. The owner can provide relevant records through the insurer’s process. Coverage evaluation and settlement remain outside our construction role, and submission of a report does not guarantee a changed decision.
Find the right help for the question
For insurance handling questions or a complaint, use Arkansas Insurance Department Consumer Services. Follow the official complaint instructions, include relevant correspondence and reference your tracking number for follow-up. Read the public-record notice before submitting sensitive documents.
For legal advice, disputed policy interpretation or a deadline that may affect your rights, contact appropriately licensed legal counsel. Ask the insurer about outstanding policy requirements while seeking assistance; do not ignore time-sensitive correspondence.
Plan repairs without assuming the denial will change
A construction inspection may still be useful to address an active leak or define a repair. Discuss temporary protection, the proposed permanent work and your payment responsibility. A desired insurance outcome should not be described as an approved construction budget.
If you request an Alden Stone consultation, tell us which property conditions or construction documents need review. We can discuss the work and practical next steps. We do not offer claim appeals, public adjusting or guaranteed insurance recovery.